INVC NEWS | New Delhi | October 18, 2026
A fixed deposit (FD) remains a popular savings option for people who want predictable returns without direct exposure to stock market fluctuations. But how much can you earn by investing ₹5 lakh in a bank FD for five years? The answer depends on the interest rate, compounding frequency, the bank’s terms and applicable taxes.
At an illustrative annual interest rate of 7%, a ₹5 lakh deposit could grow to approximately ₹7.07 lakh after five years, assuming quarterly compounding and no premature withdrawal. That would mean interest earnings of around ₹2.07 lakh before tax.
Here is the calculation, including a comparison for senior citizens and the tax rules investors should understand before opening an FD.
How much will ₹5 lakh become in five years?
The maturity amount varies with the interest rate offered by the bank. The following figures are illustrative estimates for a cumulative FD with quarterly compounding.
| Annual interest rate | Estimated maturity amount | Interest earned |
| 6.5% | ₹6,90,000 approximately | ₹1,90,000 approximately |
| 7.0% | ₹7,07,389 | ₹2,07,389 |
| 7.5% | ₹7,24,974 approximately | ₹2,24,974 approximately |
These are illustrative calculations, not guaranteed quotes from a particular bank. Actual maturity values may differ according to the bank’s calculation method, compounding rules and product terms.
How is FD interest calculated?
Banks may offer simple-interest or cumulative FD products, but cumulative deposits commonly benefit from compounding. Under this method, interest is added to the deposit at regular intervals, and subsequent interest calculations include the accumulated amount.
The compound-interest formula is:
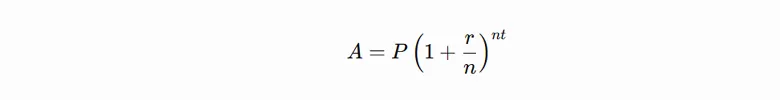
Here:
- A: Maturity amount
- P: Initial deposit of ₹5,00,000
- r: Annual interest rate of 7%
- n: Compounding frequency of four times a year
- t: Five years
With these assumptions, the estimated maturity amount is ₹7,07,389. Subtracting the original deposit of ₹5 lakh gives estimated interest earnings of ₹2,07,389.
The important point is that the final return is not simply the original deposit multiplied by the annual rate for five years. Compounding allows interest to accumulate on previously credited interest as well.
What if a senior citizen invests ₹5 lakh?
Many banks offer senior citizens an additional interest rate on eligible fixed deposits. A common example is an extra 0.50 percentage points over the rate available to regular customers, although the actual benefit depends on the bank and deposit scheme.
If a senior citizen receives an annual rate of 7.5% on a five-year cumulative FD, the estimated figures would be:
- Initial investment: ₹5,00,000
- Illustrative annual interest rate: 7.5%
- Estimated maturity amount: ₹7,24,974
- Estimated interest earned: ₹2,24,974
That is approximately ₹17,585 more in interest than the illustrative 7% FD calculation for a regular depositor.
However, senior citizens should check the applicable rate and eligibility conditions before investing. An additional rate is not universal across every bank or FD product.
Can a five-year FD help you save income tax?
A qualifying five-year tax-saving bank FD may be eligible for a deduction under Section 80C of the Income-tax Act, subject to applicable conditions.
There are several important points to remember:
- The deduction is subject to the overall Section 80C limit of ₹1.5 lakh, which is shared with other eligible investments and payments.
- The benefit is generally relevant to taxpayers using the old tax regime; deductions under Section 80C are not available under the new tax regime.
- A tax-saving FD normally has a five-year lock-in period and cannot be withdrawn prematurely except in limited circumstances permitted by the rules.
- FD interest is taxable. A tax-saving FD does not automatically make the interest tax-free.
- Banks may deduct tax at source (TDS) when the applicable conditions and thresholds are met. TDS is a tax deduction mechanism, not necessarily the final tax liability.
Investors should check the current tax rules and their own tax position before choosing a tax-saving deposit.
Is a five-year FD the right choice?
A fixed deposit can be useful for people who prioritise predictable returns and want to keep money separate from higher-volatility investments. However, choosing an FD solely because it offers a high interest rate may not be the best strategy.
Before committing ₹5 lakh, compare the bank’s interest rate, premature-withdrawal penalties, payout options and deposit terms. Also consider whether you might need the money before the five-year period ends.
Eligible bank deposits are covered by deposit insurance administered by the Deposit Insurance and Credit Guarantee Corporation (DICGC), subject to its rules and limits. The standard insurance cover is up to ₹5 lakh per depositor per bank, including principal and interest held in the same capacity and right. Therefore, a ₹5 lakh deposit plus accumulated interest may exceed the insured limit.
The bottom line
A ₹5 lakh cumulative FD earning an illustrative 7% annual rate could mature at approximately ₹7.07 lakh after five years, generating around ₹2.07 lakh in interest before tax. At an illustrative 7.5% rate, the maturity value could reach approximately ₹7.25 lakh.
The actual return depends on the bank’s rate, compounding method and terms. Compare current offers and understand the tax implications before making a final decision.